Last updated 19 October 2026 · BrightEdge Solar team
Short answer: Solar panels are special-rate plant for capital allowances. Most businesses can deduct the full cost in year one using the Annual Investment Allowance (AIA), up to £1 million a year. Companies spending more than that can claim the 50% special-rate first-year allowance on the excess. Solar panels don’t qualify for full expensing or the new 40% first-year allowance, because both are only for main-rate assets. Whatever isn’t claimed upfront goes into the special rate pool at 6% a year.
Capital allowances often make a bigger difference to a commercial solar project’s first-year cash flow than anything else, and they’re often explained wrongly. This guide covers the rules as they stand in 2026, with a worked example.
Key facts (checked 19 October 2026)
- Solar panels are special rate. The Capital Allowances Act 2001, s104A(1)(g), puts expenditure on “the provision of solar panels” in the special rate pool. GOV.UK lists solar panels under the 6% special rate pool.[1][2]
- Special rate writing-down allowance: 6% a year (reducing balance).[2]
- AIA: £1 million a year, available to companies, sole traders and partnerships, and usable on most plant and machinery including special-rate items.[3][4]
- 50% first-year allowance (special rate): companies only, new and unused assets, bought from 1 April 2023.[4][5]
- Full expensing (100%) is for main-rate plant only. Solar panels are special rate, so they get the 50% FYA instead.[5]
- 40% first-year allowance: for plant bought on or after 1 January 2026 that “qualifies for the main rate of writing down allowance”, so not solar panels.[4]
- Main-rate WDA fell from 18% to 14% from 1 April 2026 (Corporation Tax) and 6 April 2026 (Income Tax). The special rate stays at 6%.[2]
How the allowances fit together for a solar project
Think of it as a sequence. You use the most generous allowance you’re entitled to first, and anything left over drops to the next.
| Step | Allowance | Who can claim | What it gives on solar |
|---|---|---|---|
| 1 | AIA | Companies, sole traders, partnerships | 100% of the cost in the year of purchase, up to £1m (shared across the group, and reduced for short accounting periods)[3] |
| 2 | 50% special-rate FYA | Companies paying Corporation Tax | 50% of any cost the AIA doesn’t cover, in year one. The rest goes to the special rate pool[5] |
| 3 | Special rate pool WDA | Everyone | 6% a year on the reducing balance[2] |
| ✗ | Full expensing | Companies, but main-rate assets only | Not available for solar panels[5] |
| ✗ | 40% FYA | Main-rate assets only, from 1 Jan 2026 | Not available for solar panels[4] |
So, for almost every SME project we quote, from a 30 kWp workshop roof to a 300 kWp estate, the whole system can usually be written off in year one through the AIA, as long as the business hasn’t already used its AIA on other spending that year.
A worked example
Our business solar grants and costs page gives a typical installed price of £50,000–£65,000 (ex VAT) for a 100 kWp system. Take £57,500 as an illustration, bought by a limited company paying the main rate of Corporation Tax (25% on profits above £250,000).[6]
| Scenario | Year-one deduction | Year-one tax saving at 25% | What’s left |
|---|---|---|---|
| A. AIA available | £57,500 (100%) | £14,375 | £0 |
| B. AIA used up, company claims 50% FYA | £28,750 (50%) | £7,187.50 | £28,750 into the special rate pool, then 6% a year (£1,725 in year two, saving £431.25) |
| C. Only WDA (rare; e.g. a second-hand system) | £3,450 (6%) | £862.50 | £54,050 to keep writing down |
For a company on the 19% small profits rate (profits of £50,000 or less), scenario A saves £10,925 in year one. Companies with profits between £50,000 and £250,000 pay an effective rate set by Marginal Relief.[6]
This is an illustration, not a quote. Your figures depend on your accounting period, profits, group structure and other capital spending that year.
Sole traders, partnerships and farmers
- AIA applies to you. A farming partnership or sole trader buying a shed-roof array can usually deduct the full cost through the AIA.[3]
- The 50% FYA doesn’t. It’s companies only.[5] This rarely matters, because few unincorporated businesses spend more than £1m on plant in a year.
- Cash basis: if you use the cash basis, GOV.UK says you can only claim capital allowances on business cars. Equipment is handled as an expense instead. Ask your accountant which basis you’re on.[3]
- The main-rate WDA change applies from 6 April 2026 for Income Tax.[2]
Our farm installs, such as the 19.8 kWp asbestos-shed array at North Dalton, are typically owned by unincorporated businesses, so this section applies to many of our agricultural clients.
What about batteries, EV chargers and installation costs?
- Installation, scaffolding and electrical work that’s part of providing the panels is normally included in the cost of the plant. HMRC’s checker asks for the cost “including delivery and installation charges”.[5]
- Battery storage: GOV.UK lists solar panels in the special rate pool but doesn’t say how a battery is treated, and the answer can depend on how the battery is installed and used. Don’t assume it qualifies for full expensing or the 40% FYA. Speak to your accountant about how to allocate a battery before you claim.
- EV charging points: equipment for EV charge points bought new before April 2027 can qualify for a 100% first-year allowance.[4] That’s worth knowing if you’re adding chargers with the array.
- Leasing and PPAs: assets bought to lease to others are generally excluded from full expensing and the 50% FYA. Under a solar PPA, the funder owns the panels and claims the allowances, not you.[5] See solar PPA and solar finance.
In practice: a 69.16 kWp manufacturer roof in Rotherham
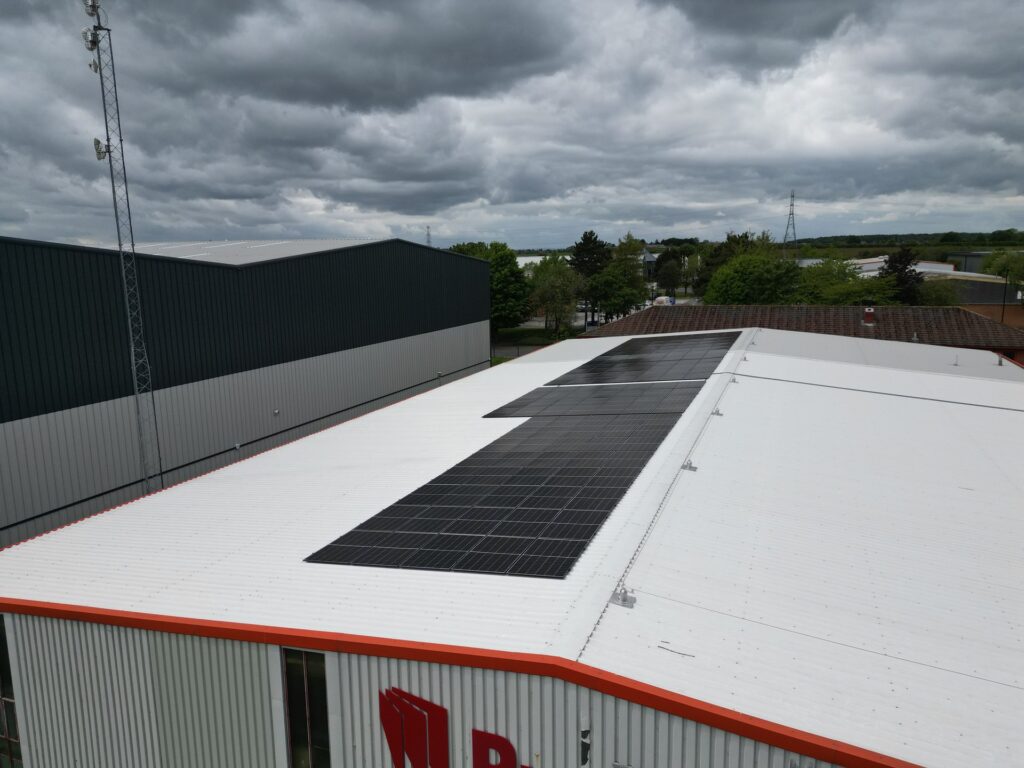
For a local manufacturer in Rotherham, we installed 69.16 kWp of SolarEdge rooftop solar with optimisers, designed to limit the losses from partial shading. A project of that size falls well within a single year’s £1m AIA, so a company like this can normally deduct the full cost against that year’s profits.
Timing your purchase
- AIA and FYAs are claimed in the period you buy the asset. For AIA, GOV.UK says the purchase date is when the contract is signed if payment is due within 4 months, or when payment is due if it’s later.[3] If your year-end is coming up, talk to your accountant about when to sign.
- Hire purchase: you can claim on the payments under the contract once you start using the item, but not on the interest.[3]
- Year one vs over time: AIA gives the relief in year one. In return there’s nothing left to write down later. Most businesses prefer the cash-flow benefit.
Combined with the business rates exclusion for onsite solar until 2035 (see do you pay business rates on solar panels?), the tax position for a business that owns its system outright is usually very favourable.
FAQ
Can I claim capital allowances on solar panels?
Yes. Solar panels are plant and machinery in the special rate pool. Most businesses can claim 100% in year one through the Annual Investment Allowance, up to £1m a year.[1][3]
Do solar panels qualify for full expensing?
No. Full expensing is for main-rate plant. Solar panels are special rate, so companies use the 50% first-year allowance for any cost beyond their AIA.[5]
Does the 40% first-year allowance apply to solar panels?
No. The 40% FYA, for purchases from 1 January 2026, requires assets that qualify for the main rate of writing-down allowance. Solar panels are special rate.[2][4]
What is the writing-down allowance on solar panels?
6% a year on the reducing balance in the special rate pool, for any cost not covered by AIA or the 50% FYA.[2]
Can sole traders and farmers claim?
Yes, through the AIA (unless they use the cash basis, where equipment is treated as an expense). The 50% FYA is for companies only.[3][5]
Get a system priced, then talk to your accountant
We’re an MCS-certified commercial installer based in Beverley. We give you an itemised quote (panels, inverters, mounting, scaffolding, electrical and DNO costs) so your accountant can allocate it properly. Send us your bills or half-hourly data and we’ll model the system and its payback.
Book a free survey · Call 01482 765063
This guide explains the rules in general terms and isn’t tax advice. Speak to your accountant or tax adviser about your business.
Sources
- Capital Allowances Act 2001, s104A(1)(g), solar panels as special rate expenditure: https://www.legislation.gov.uk/ukpga/2001/2/section/104A (checked 19 Oct 2026)
- GOV.UK, Writing down allowances: rates and pools (main pool 14% from April 2026, special rate pool 6%, solar panels listed): https://www.gov.uk/work-out-capital-allowances/rates-and-pools (checked 19 Oct 2026)
- GOV.UK, Claim capital allowances: Annual investment allowance: https://www.gov.uk/capital-allowances/annual-investment-allowance (checked 19 Oct 2026)
- GOV.UK, Claim capital allowances (full guide, including 100% FYAs and the 40% first-year allowance): https://www.gov.uk/capital-allowances/print (checked 19 Oct 2026)
- HMRC, Check if you can claim full expensing or 50% first year allowances: https://www.gov.uk/guidance/check-if-you-can-claim-full-expensing-or-50-first-year-allowances (checked 19 Oct 2026)
- GOV.UK, Corporation Tax rates and reliefs: https://www.gov.uk/corporation-tax-rates (checked 19 Oct 2026)